
What Is Your Life Rate?
If you own a home with a mortgage rate below 5%, there’s a good chance you know that number.
You probably remember exactly what rate you locked in. You may even tell yourself, “There’s no way I’m giving up my 3.25% mortgage.”
And we understand why.
But here’s a question worth asking:
Do you know your life rate?
Your mortgage rate is only one piece of your financial picture.
Your life rate considers the interest you are paying across all of your debt, your mortgage, credit cards, HELOC, car loans, boat loans, RV loans and other financed purchases.
And for many American households, that number can be dramatically higher than the rate on their mortgage.
Your Mortgage Rate May Be Low. Your Life Rate May Not Be.
Let's say you have a mortgage at 4%.
That sounds great, and it is.
But what if you also have:
- Credit card debt at 20%+
- A HELOC at 8%–10%
- A vehicle loan at 7%
- A boat or RV loan at 8%–10%
Your mortgage may be inexpensive, but the blended cost of your household debt can be much higher.
Estimates put the average American's overall borrowing cost, or “life rate”, at roughly 11.5%.
That changes the conversation.
Instead of asking only:
“What will my new mortgage rate be?”
It may be worth asking:
“What is my life rate today, and could I improve my overall financial picture while getting the home and lifestyle I actually want?”
What If You Don't Love Your Home Anymore?
There is another piece of this conversation that often gets overlooked.
Maybe you bought your home 10 years ago because it was the right home for your family at the time.
But life changes.
Maybe your kids have grown up. Maybe the grandkids are coming around more often. Maybe you want a home office, a bigger garage, more storage or a better floor plan.
Maybe you're tired of being able to reach out and touch your neighbor's house.
Maybe you dream about having a little more land, a place where your kids or grandkids can run through the trees, build a fort, ride bikes, fish in a pond or simply have room to breathe.
And maybe your current home needs a new roof, air conditioner, water heater or other major repairs.
You may love your interest rate.
But do you love your home?
That's an important distinction.
Home Equity Can Create Options
For homeowners who have built significant equity, selling their current home may create an opportunity that wasn't available a few years ago.
Rather than simply moving that equity into another house, some homeowners may choose to use a portion of their proceeds to eliminate higher-interest debt.
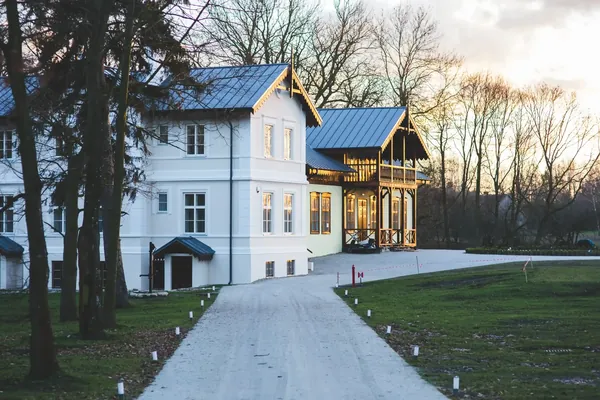
The result could be a new home, a new lifestyle and a significantly different debt picture.
For example, imagine selling a home with substantial equity and using a portion of that equity to pay off credit cards, a HELOC, vehicle loans or other higher-interest debt.
Yes, your new mortgage rate may be higher than the rate you left behind.
But you could also have:
- A newer home
- A better floor plan
- A new-home warranty
- No immediate roof replacement hanging over your head
- A new HVAC system
- A new water heater
- Less high-interest debt
- A lifestyle that better fits the way you live today
That deserves consideration.
What Does Acreage Have to Do With It?
At Elk Ridge Homes, we believe the conversation goes beyond the house.
We build homes on acreage because we believe where you live matters.
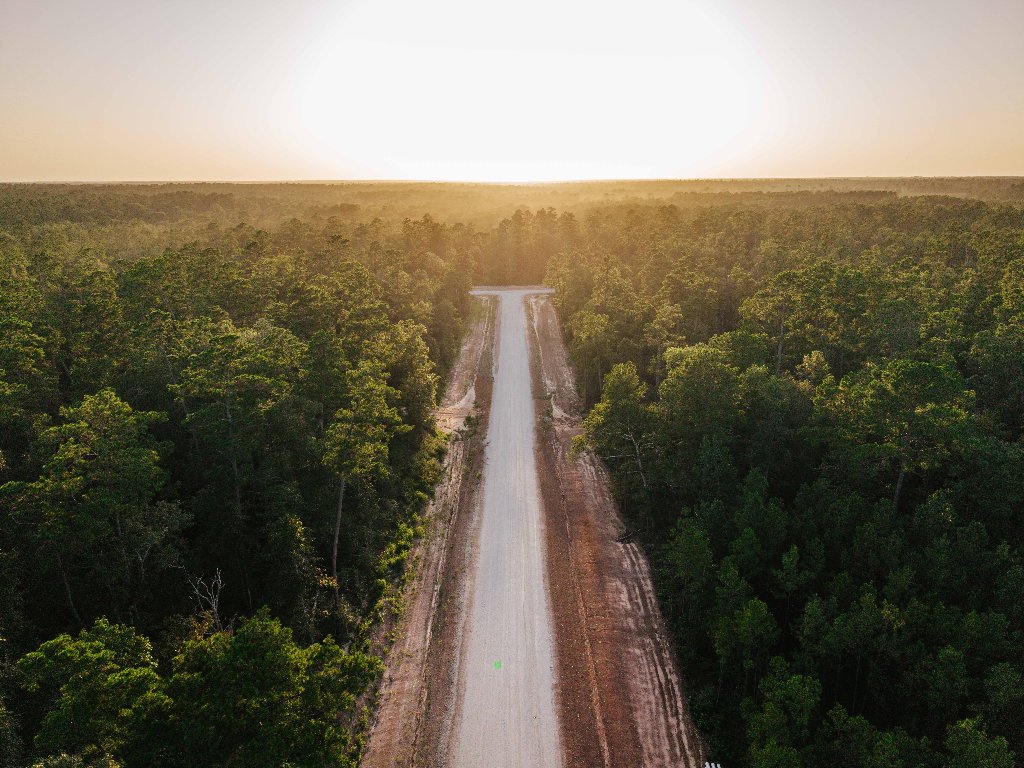
Imagine trading a neighborhood where homes are 10 feet from you on every side for a wooded homesite with room to breathe.
Imagine your kids or grandkids running through a large backyard instead of playing on a small patch of grass.
Imagine having room for a workshop, a pool, a garden, a dog, or simply a quiet place to sit outside and enjoy the trees.
And in many of our communities, homeowners can also benefit from low property tax rates, which can make the overall cost of ownership more attractive.
That is not just a housing decision.
That's a lifestyle decision.
The Low Rate Isn't the Whole Story
We aren't suggesting that everyone with a low mortgage rate should sell their home.
Far from it.
If you love your home, your finances work well and your current lifestyle fits your family, keeping that low-rate mortgage may be the smartest decision.
But if you are sitting in a home you no longer love simply because you're afraid to give up a low interest rate, it may be worth looking at the entire picture.
Look at your:
- Mortgage rate
- Credit card rates
- HELOC rate
- Auto loans
- Boat and RV loans
- Monthly debt payments
- Home maintenance costs
- Property taxes
- Homeowners insurance
- Available home equity
- And, perhaps most importantly, the lifestyle your home provides
Then ask yourself:
“Am I protecting a low mortgage rate, or am I protecting the life I actually want to live?”
Those aren't always the same thing.
What Is Your Life Rate?
Before making a move, talk with your lender and financial advisor about your specific situation. Understand your equity, your current debt, your potential new payment and the full cost of moving.
At Elk Ridge Homes, we don't believe our job is simply to sell you a house.
Our job is to be your trusted advisor.
If you're considering selling your current home, using your equity, paying down higher-interest debt and moving into a new home on acreage in the greater Houston area, we'd be happy to help you look at the possibilities.
You may discover that the question isn't simply whether you can afford a new mortgage rate.
The better question may be:
“What is my life rate, and what would it take to build a life I love?”
Reach out to Elk Ridge Homes today. Let us help you look at the numbers, the options and the lifestyle you're really trying to create.